Preparing a rent-to-own application with bad credit
By Hannah Haddad, Editorial Director · Updated 2026-09-30
This is general information, not financial or legal advice. Talk to a licensed mortgage professional and a real estate lawyer about your own situation.
A weak credit history does not automatically close the door on rent to own, but it changes what you should check and what you should expect. Preparing well makes your application clearer and your decision safer.
Know your file
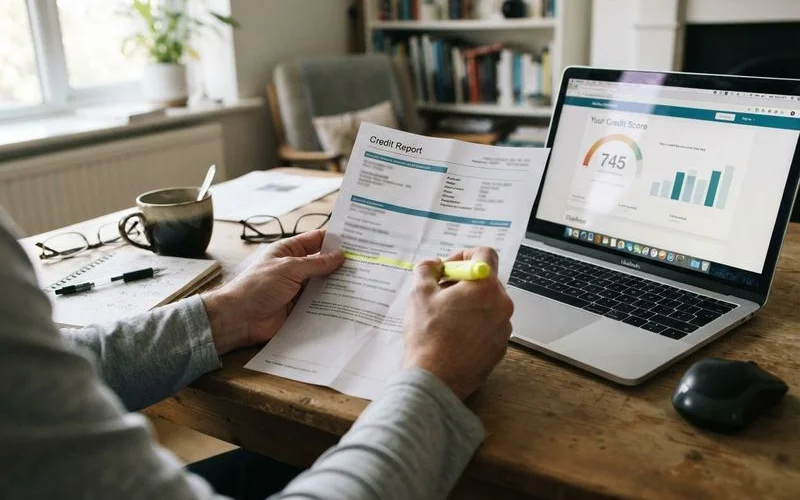
Request your credit report from both Canadian bureaus and read every line. Errors are common enough that checking is worth the time. Note any collections, missed payments or settled accounts, and be ready to explain them in plain terms.
What to gather
| Item | Why it helps |
|---|---|
| Credit reports | Shows what a provider will see |
| Proof of income | Shows ability to pay |
| Notice of assessment | Confirms income on file with the tax agency |
| Bank statements | Shows payment habits |
| A short written explanation | Puts past problems in context |
| Savings record | Supports the option fee |
What providers look at
Programs differ. Some place weight on steady income and a clear payment history over the past year or two rather than the score alone. Others require a larger upfront fee or a higher monthly premium. Ask each one the same questions so the answers can be compared.
Our bad credit and self-employed friendly hub groups providers that say they work with harder files. A listing there is not a promise of approval, and every program still has its own rules.
Watch the cost
A weaker file can mean more of your money tied up in fees. Before agreeing, work out what you would lose if you did not buy, and whether you could realistically qualify for a mortgage by the end. A lender will look at your file again at that point, so use the term to improve it.
Warning signs
- A promise that approval is certain.
- Pressure to pay before the contract is shown.
- Steering you to one particular mortgage contact.
Build a plan
- Pull and review your credit reports.
- Fix errors and pay down balances where you can.
- Speak with a licensed mortgage professional about a realistic timeline.
- Have a lawyer read the agreement.
Telling your story clearly
Providers and lenders see many files, and a short, factual explanation helps. Say what happened, when it happened, and what has changed since. Avoid blaming and avoid long histories. A job loss two years ago followed by steady payments since is a clearer story than a list of excuses. Keep it to a paragraph and keep supporting documents ready in case someone asks.
Free and low-cost help
Non-profit credit counselling services exist in Ontario and can help you build a repayment plan. Some offer free initial sessions. Check that any service you use is a registered non-profit or otherwise reputable before sharing financial details, and be wary of any business that charges large upfront fees to repair credit. Those fees do not remove accurate information from your report, and nothing legitimate can promise to.
Time is the main tool
Most credit repair comes down to on-time payments and lower balances sustained over months. That is why a longer option period can matter for someone with weaker credit, and why the first lender conversation should happen early rather than at the end. If your situation involves a past bankruptcy or consumer proposal, or irregular self-employed income, the circumstances differ and are worth discussing with a professional who handles those cases directly.
Our glossary has a short entry on credit rebuilding for a quick definition. How we assess listings is on the Scoring Method page, and the directory home leads to the other hubs.
FAQ
- Can I apply for rent to own with a low credit score?
- Some programs consider applicants with weaker credit, but terms vary and a lender will still assess you at the end. Ask each provider how it treats credit.
- Should I fix my credit first?
- Starting the work early helps, and you do not have to finish before you talk to a provider.
- What documents should I have ready?
- A credit report, proof of income, ID, and records of any past debt settlement.
- Will a weaker file cost me more?
- Possibly, through higher fees or premiums. Ask for the full cost in writing and compare.