Getting mortgage-ready during a rent-to-own term
By Hannah Haddad, Editorial Director · Updated 2026-09-26
This is general information, not financial or legal advice. Talk to a licensed mortgage professional and a real estate lawyer about your own situation.
The rent-to-own term is a window, not a guarantee. What you do inside it decides whether a lender is ready to say yes at the end. Below is a plain checklist, laid out by time, for tenants working toward that approval.
A timeline
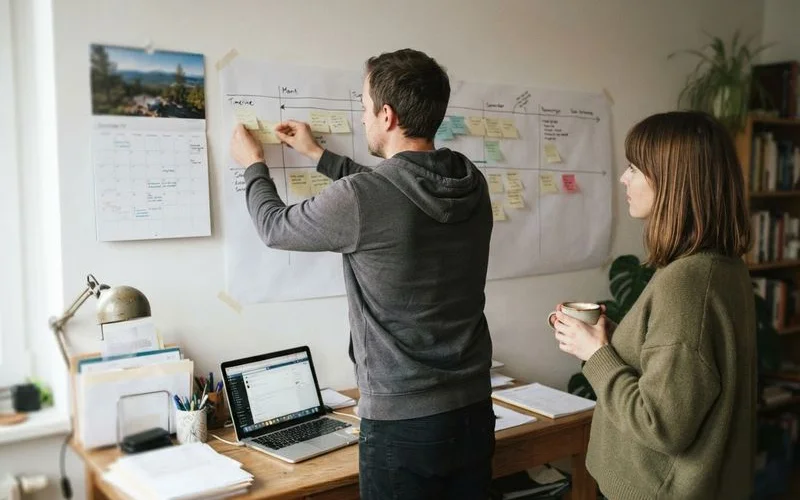
| When | Focus | Examples |
|---|---|---|
| Before signing | Know your starting point | Pull your credit report; talk to a licensed mortgage professional |
| First 6 months | Fix what you can | Pay on time, reduce card balances, correct errors |
| Months 6 to 18 | Build a record | Keep income steady, gather notices of assessment |
| Final year | Get lender-ready | Confirm down payment, update documents, seek pre-qualification |
| Final 3 months | Apply | Submit the application before the deadline |
Credit
Late payments and high card balances are the first things a lender notices. Paying everything on time and keeping balances well under your limits is slow work, and it needs months, not weeks. Our glossary covers credit rebuilding in short form; the practical point is that the earlier you start, the more of the term it can help.
Income
Employed buyers typically show pay records and tax slips. Self-employed buyers usually need more, such as notices of assessment over several years. Whichever applies, start collecting documents early and keep them organised. Lenders vary on what they accept, which is why asking early matters.
Debt and the stress test
Lenders compare your debts to your income and, for federally regulated lenders, check that you could afford a higher qualifying payment. Lowering monthly debts before applying can shift those ratios. A mortgage professional can explain how the tests apply to you.
Savings
Check how rent credits and your own savings fit together. A credit recorded in the contract is only useful if the lender and the seller treat it as part of your down payment, so confirm that with both.
Finding help
Our mortgage and credit support hub lists brokers and credit-focused providers. Reviewers often describe the better-regarded ones as responsive and clear in explaining each step, but treat those comments as individual experiences, and always confirm licensing. As the option period nears its end, the guide to choosing a mortgage broker covers what to ask.
Keep a file
Pre-qualification versus approval
Pre-qualification is an early indication from a lender or broker of what you might be able to borrow, based on information you give them. It is not a commitment to lend. Approval comes later, after the lender checks your documents and the property. Use pre-qualification to learn what needs fixing, and treat approval as something that happens near the end, with the property in view.
Common obstacles during the term
New debt is a frequent one: a car loan or a new credit card can shift your ratios. Job changes are another, since some lenders want to see a track record in a role. Missed payments of any kind, including on small accounts, set the clock back. Before taking on anything new, ask a mortgage professional how it would look on your file.
Staying on track
Set a reminder every three months to check your credit, update your savings figure, and review your documents. Short, regular reviews catch problems while they are small. Sit down with a licensed professional twice a year if you can, and bring your contract so they can see how the credits and dates fit with a lender’s process. None of this guarantees approval, but it makes sure that if a lender says no, you will already know the reasons and have had time to respond.
Create one folder for your agreement, payment records and credit statements, and update it monthly. At the end of the term, a tidy file saves weeks. For how we assess listings, see our Scoring Method, and for everything else the home page.
FAQ
- When should I first talk to a mortgage professional?
- At or before signing, then again at regular points through the term. Early advice leaves time to fix issues.
- What do lenders usually look at?
- Credit history, income and its documentation, existing debts and down payment. Rules differ by lender.
- Can rent payments help my credit?
- Only if they are reported. Ask whether your payments are, and do not assume they are.
- Is there a guaranteed approval?
- No. A lender decides based on your file at the time you apply.